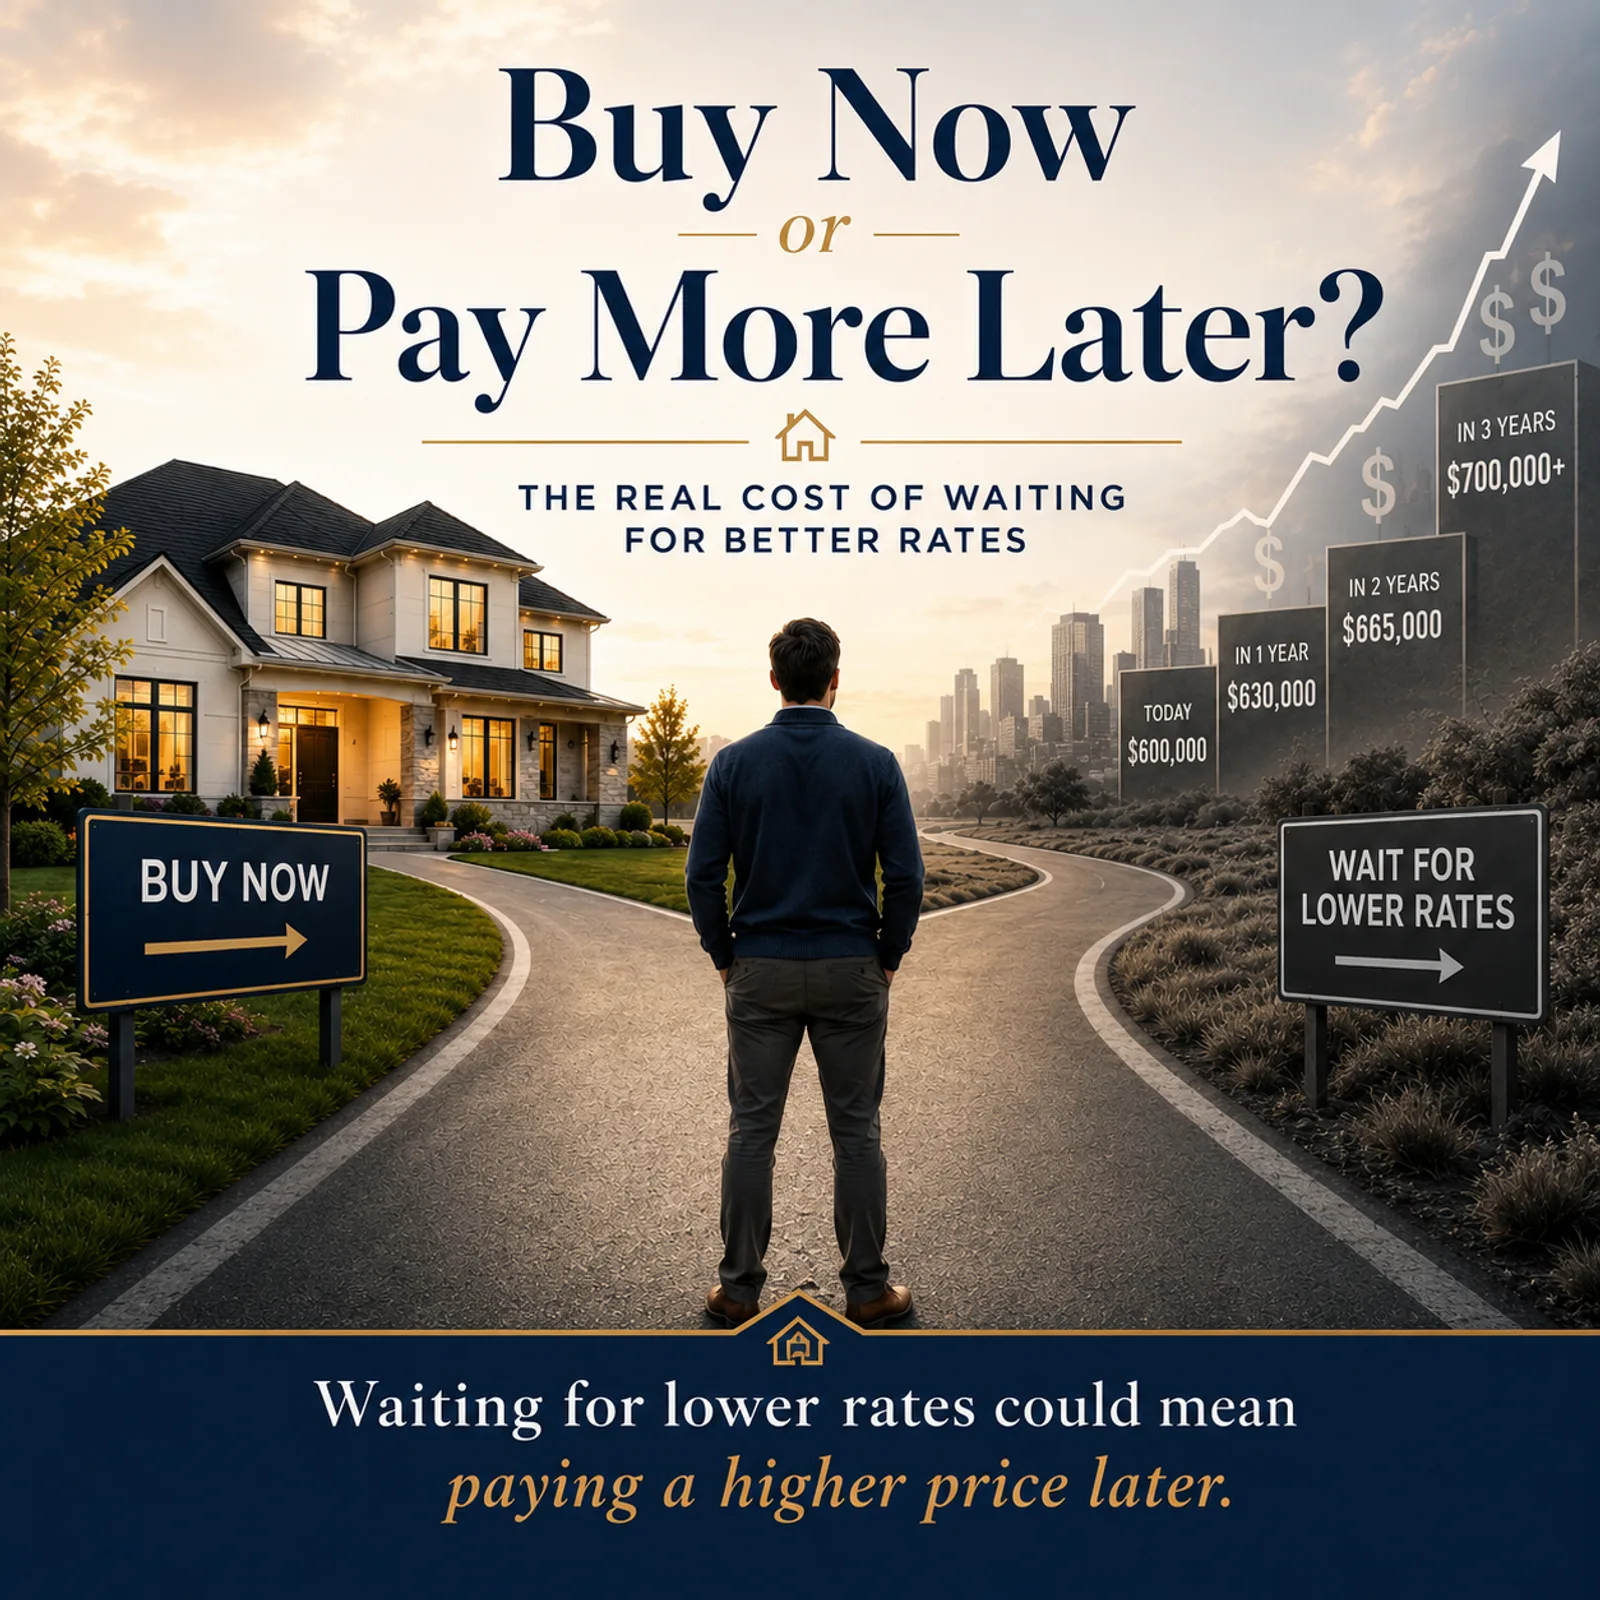
"I'm going to wait for interest rates to fall before I jump into the housing market."
On the surface, it sounds incredibly logical. Mortgage rates have been higher than we'd like, which naturally means higher monthly payments. It feels safer to assume that waiting for a lower rate will save you a bundle.
In reality, no one can promise what prices or rates will do next. Whether waiting helps or hurts depends on how home prices move, what rates are actually available when you re-enter the market, and whether you are personally ready to buy. The honest answer is that waiting can cost you in some scenarios and save you in others, so we want to lay out the math on both sides.
Here is what we can do: walk through the numbers, assume nothing, and show you three clearly labeled hypothetical scenarios side by side so you can see the range of outcomes for homebuyers in Murrieta, Temecula, Menifee, and across Southwest Riverside County.
The Friction of Price Appreciation
To understand why the "wait-and-see" strategy can backfire, you have to look closely at home price appreciation. And to be fair to the other side, you also have to consider what the numbers look like if prices do not rise at all.
Home prices in Southern California have risen over long stretches of recent history, but past performance is no promise of what the next 12 months will bring. Prices could rise, hold steady, or ease back, depending on rates, inventory, and buyer demand. That is why we built the comparison below as three clearly labeled hypothetical scenarios rather than a single prediction.
For a current look at where Murrieta and Temecula actually stand today, see our local market report. (Note: We are using a baseline $800,000 purchase price for the illustration below to keep the math clear and easy to follow, and every assumption is stated explicitly. The same framework applies whether you are looking at a $500,000 condo or a $1.5 million estate in Menifee, Temecula, or anywhere in the Inland Empire.)
The 12-Month Delay Cost Breakdown
The table below puts buying today side by side with the three possible price paths a 12-month wait could take, using the exact same assumptions for every column so you can compare them directly.
| Assumption | Buy Today (reference) | Wait: Prices Rise (+5%) | Wait: Prices Flat | Wait: Prices Fall (-5%) |
|---|---|---|---|---|
| Purchase Price (hypothetical) | $800,000 | $840,000 | $800,000 | $760,000 |
| Down Payment (20%) | $160,000 | $168,000 | $160,000 | $152,000 |
| Loan Amount & Term | $640,000, 30-year fixed | $672,000, 30-year fixed | $640,000, 30-year fixed | $608,000, 30-year fixed |
| Interest Rate (assumed) | 6.5% | 6.0% | 6.0% | 6.0% |
| Monthly Principal & Interest | ~$4,045 | ~$4,030 | ~$3,840 | ~$3,645 |
| Property Taxes (est./mo) | ~$733 | ~$770 | ~$733 | ~$697 |
| Homeowners Insurance (est./mo) | ~$150 | ~$150 | ~$150 | ~$150 |
| HOA / Assessments (est./mo) | ~$200 | ~$200 | ~$200 | ~$200 |
| Maintenance (est./mo) | ~$250 | ~$250 | ~$250 | ~$250 |
| Total Monthly Housing Cost | ~$5,380 | ~$5,400 | ~$5,170 | ~$4,940 |
| Alternative Monthly Rent (comparison) | ~$3,500 | ~$3,500 | ~$3,500 | ~$3,500 |
| Buyer Closing Costs (one-time, est.) | ~$12,000 | ~$12,600 | ~$12,000 | ~$11,400 |
| Eventual Sale Costs (est., shown separately) | ~$44,000 | ~$46,200 | ~$44,000 | ~$41,800 |
Hypothetical examples for illustration only. They are not forecasts of future prices or rates, and they are not loan quotes. All three wait scenarios use the same assumed 6.0% rate so the only difference between them is price. Your actual rate, loan terms, and payment will depend on your credit, income, loan program, and the market at the time you buy. Taxes, insurance, HOA fees, maintenance, and rent vary by property and neighborhood. Eventual sale costs are estimates of typical agent commissions and conveyance fees; any increase in value is only realized at a sale, net of those costs.
Here is what the comparison shows. In the rising-price scenario, you wait a year, rates ease a little, and your total monthly cost lands in almost the same place as buying today, roughly $5,400 versus $5,380, while your down payment is $8,000 higher. In the flat-price scenario, waiting lowers your monthly cost by about $210. In the falling-price scenario, waiting helps more, about $440 less per month.
But those numbers are only part of the story. While you wait, you are likely paying rent, and rent is an expense that builds no ownership. At the $3,500 per month estimate used above, 12 months of waiting costs roughly $42,000 in rent you will not get back. And no one can promise which scenario will actually happen. If prices rise faster than the example, waiting becomes more expensive; if prices fall, it becomes less expensive. The outcome depends on the future, which no one controls.
One more thing worth being honest about: any increase in your home's value is an estimate on paper until you sell. Equity is not automatically banked in your pocket. When you eventually sell, typical costs such as agent commissions and conveyance fees are deducted from the sale price, so the value you actually keep is the sale price minus those transaction costs.
The Hidden Danger of Pent-Up Demand
There is another critical factor most buyers fail to calculate: human behavior and competition.
In past cycles, we have sometimes seen the market accelerate when mortgage rates eased, as buyers who had been sitting on the sidelines entered at the same time. Right now there may be buyers waiting for a specific rate number, and if rates ease meaningfully, some of them could enter the market together.
That is one possible market pattern, not a prediction. When more buyers compete for a limited number of homes in neighborhoods across Murrieta, Temecula, and Menifee, simple supply and demand can put pressure on prices, and some homes can attract multiple offers. It is equally possible that inventory grows, demand softens, or prices hold steady. We simply do not pretend to know which path the market will take.
What we can promise is that we will tell you what we are actually seeing in the neighborhoods you care about, so you can make an informed decision either way.
Control the Variables You Can
No one has a crystal ball, and no one can definitively predict exactly where home prices or mortgage rates will go. What buying now does offer is certainty about one part of the equation: the price you pay and the rate you lock in today are known.
For a buyer who is financially ready, that kind of certainty has real value. Because every buyer's situation is different, your actual rate, loan terms, and monthly payment will depend on your credit, income, and the loan program that fits you; the examples above are illustrations, not quotes or promises.
A common question is whether you can refinance later if rates drop. Refinancing can make sense in some situations, but it is not guaranteed to be available or worthwhile. It depends on loan eligibility, how much equity you have accumulated, the closing costs involved, and the loan terms available at the time. Your lender can help you compare the numbers when the time comes.
The bottom line: You can marry the house, but you're only dating the rate.
Get Your Personalized "Cost of Waiting" Breakdown
Want to see how these numbers shake out for your specific budget, price point, or target neighborhood in Murrieta, Temecula, or Menifee? Let's map it out together. Connect with us today for a personalized breakdown, and we will walk through your scenario without pushing you in any direction.
Decided to Wait? That Is a Completely Reasonable Choice.
There is nothing wrong with waiting until the numbers work for you. If you are not ready to buy yet, you do not have to be. Our Not Ready to Buy Yet page walks through what you can do in the meantime, from saving and credit to monitoring the market, all with zero pressure.
Related Resources
Laura Holbert
Real Estate Broker, REALTOR® · CA DRE# 01932682 · Team Integrity Realty
Have Questions About When to Buy?
We're always happy to walk through the numbers with you — no pressure, no obligation.